 Qyndarix Thalendros
How to Set a Realistic Home-Buying Budget begins by facing one clear fact: overstretching for a house is the single fastest way to turn a dream into months of stress. This guide shows how to map income, debts, savings, and true ownership costs so they fit a livable monthly number. It uses lender rules and honest, practical checks to help buyers pick a comfortable price range in 2026 without pretending future raises or cuts won’t happen.
Key Takeaways
- Setting a realistic home-buying budget prevents financial stress by aligning monthly housing costs with actual income, debts, and living expenses.
- Calculate your debt-to-income (DTI) ratio, including projected mortgage payments, to ensure you meet lender requirements and maintain affordability.
- Account for all ongoing homeownership expenses beyond the mortgage, such as taxes, insurance, utilities, and maintenance costs.
- Develop a comfortable monthly housing payment based on take-home pay and essential expenses, then seek lender preapproval within that range.
- Avoid relying on optimistic income projections or lender maximums; prioritize personal financial comfort to maintain stability and emergency savings.
- A well-planned home-buying budget turns a house purchase into a sustainable home, reducing risks from unexpected expenses or income changes.
Why A Realistic Home-Buying Budget Matters
How To Set A Realistic Home-Buying Budget: A Practical 2026 Guide To Afford The Right House Without Stretching Yourself Thin
A realistic budget prevents common financial harm: missed payments, drained emergency funds, and forced sales. Lenders often suggest housing costs at roughly 28–31% of gross income, and total debts within DTI limits. But the real test is whether a monthly payment leaves room for groceries, transportation, child care, and a repair cushion.
Buyers who ignore this run into avoidable panic: a sudden layoff, a roof leak, or a higher interest rate can turn a manageable payment into a crisis. A realistic budget reduces those risks by forcing a clear look at present cash flow and expected homeowner costs. It also gives negotiating power: knowing a comfortable price range helps buyers walk away from emotionally driven bids that exceed long-term capacity.
Practical moment: someone who thought they could stretch to a $2,500 housing payment discovered, after mapping expenses, that their real comfortable number was $1,750, enough to save for emergencies and still afford repairs without stress. That difference determines whether a house is lived in or simply endured.
Determine Your Financial Baseline
Answer first: how much money really flows and out each month? That baseline decides the rest.
Track Income, Expenses, And Emergency Savings
Start with gross monthly income, salary, bonuses, freelance work. Lenders focus on gross numbers, but buyers must plan on take-home pay. List fixed monthly outflows: minimum credit card payments, car loans, student loans, child support, and subscription services. Then list variable spending: groceries, gas, dining out. Use three months of bank statements for accuracy.
Adopt a simple framework like 50/30/20 to test flexibility: needs 50%, wants 30%, savings/debt 20%. If housing push moves needs above 50%, the budget is risky. Buyers should also confirm an emergency fund of 3–6 months of essential expenses before closing. A common real-world slip: people include promised promotions in income calculations. That optimism often fails: plan with current earnings.
Calculate Your Debt-To-Income Ratio
Short answer: compute DTI now and with the projected mortgage to see if lenders and sanity align.
DTI formula: total monthly debt payments ÷ gross monthly income × 100. Compute two DTIs: front-end (projected housing payment ÷ gross income) and back-end (all debts including housing ÷ gross income). Many lenders look for back-end DTI below about 43% and front-end near 28–31%, but specific programs vary.
Concrete check: if gross monthly income is $6,000 and existing debts total $1,200, current DTI is 20%. Adding a $1,500 mortgage payment raises back-end DTI to 45%, outside common comfort and some lender limits. That simple math often forces a lower price target or a larger down payment.
Understand Mortgage Costs And Ongoing Homeownership Expenses
Fact first: the monthly mortgage bill is more than principal and interest. It typically includes taxes, insurance, and possibly HOA fees.
Mortgage payments contain principal and interest, which change dramatically with term and rate. A 30-year mortgage spreads principal out, lowering monthly cost but increasing total interest. Closing costs usually run 2–5% of the purchase price: buyers must save for that plus the down payment.
Ongoing owner costs include property taxes, homeowners insurance, utilities, routine maintenance, and occasional repairs. Use concrete estimates: for many U.S. homes, budget 1–3% of the home’s value annually for maintenance. For a $300,000 house, that’s $3,000–$9,000 a year, or $250–$750 a month, on average. Add typical utilities and insurance to see the full monthly burden.
To connect budgeting to real examples, consult a breakdown like the site’s analysis of monthly ownership costs for realistic projections. A focused internal resource helps translate abstract percentages into local tax and insurance dollars: the article on true monthly costs provides those line-item examples.
Build Your Budget, Get Preapproved, And Choose A Comfortable Price Range
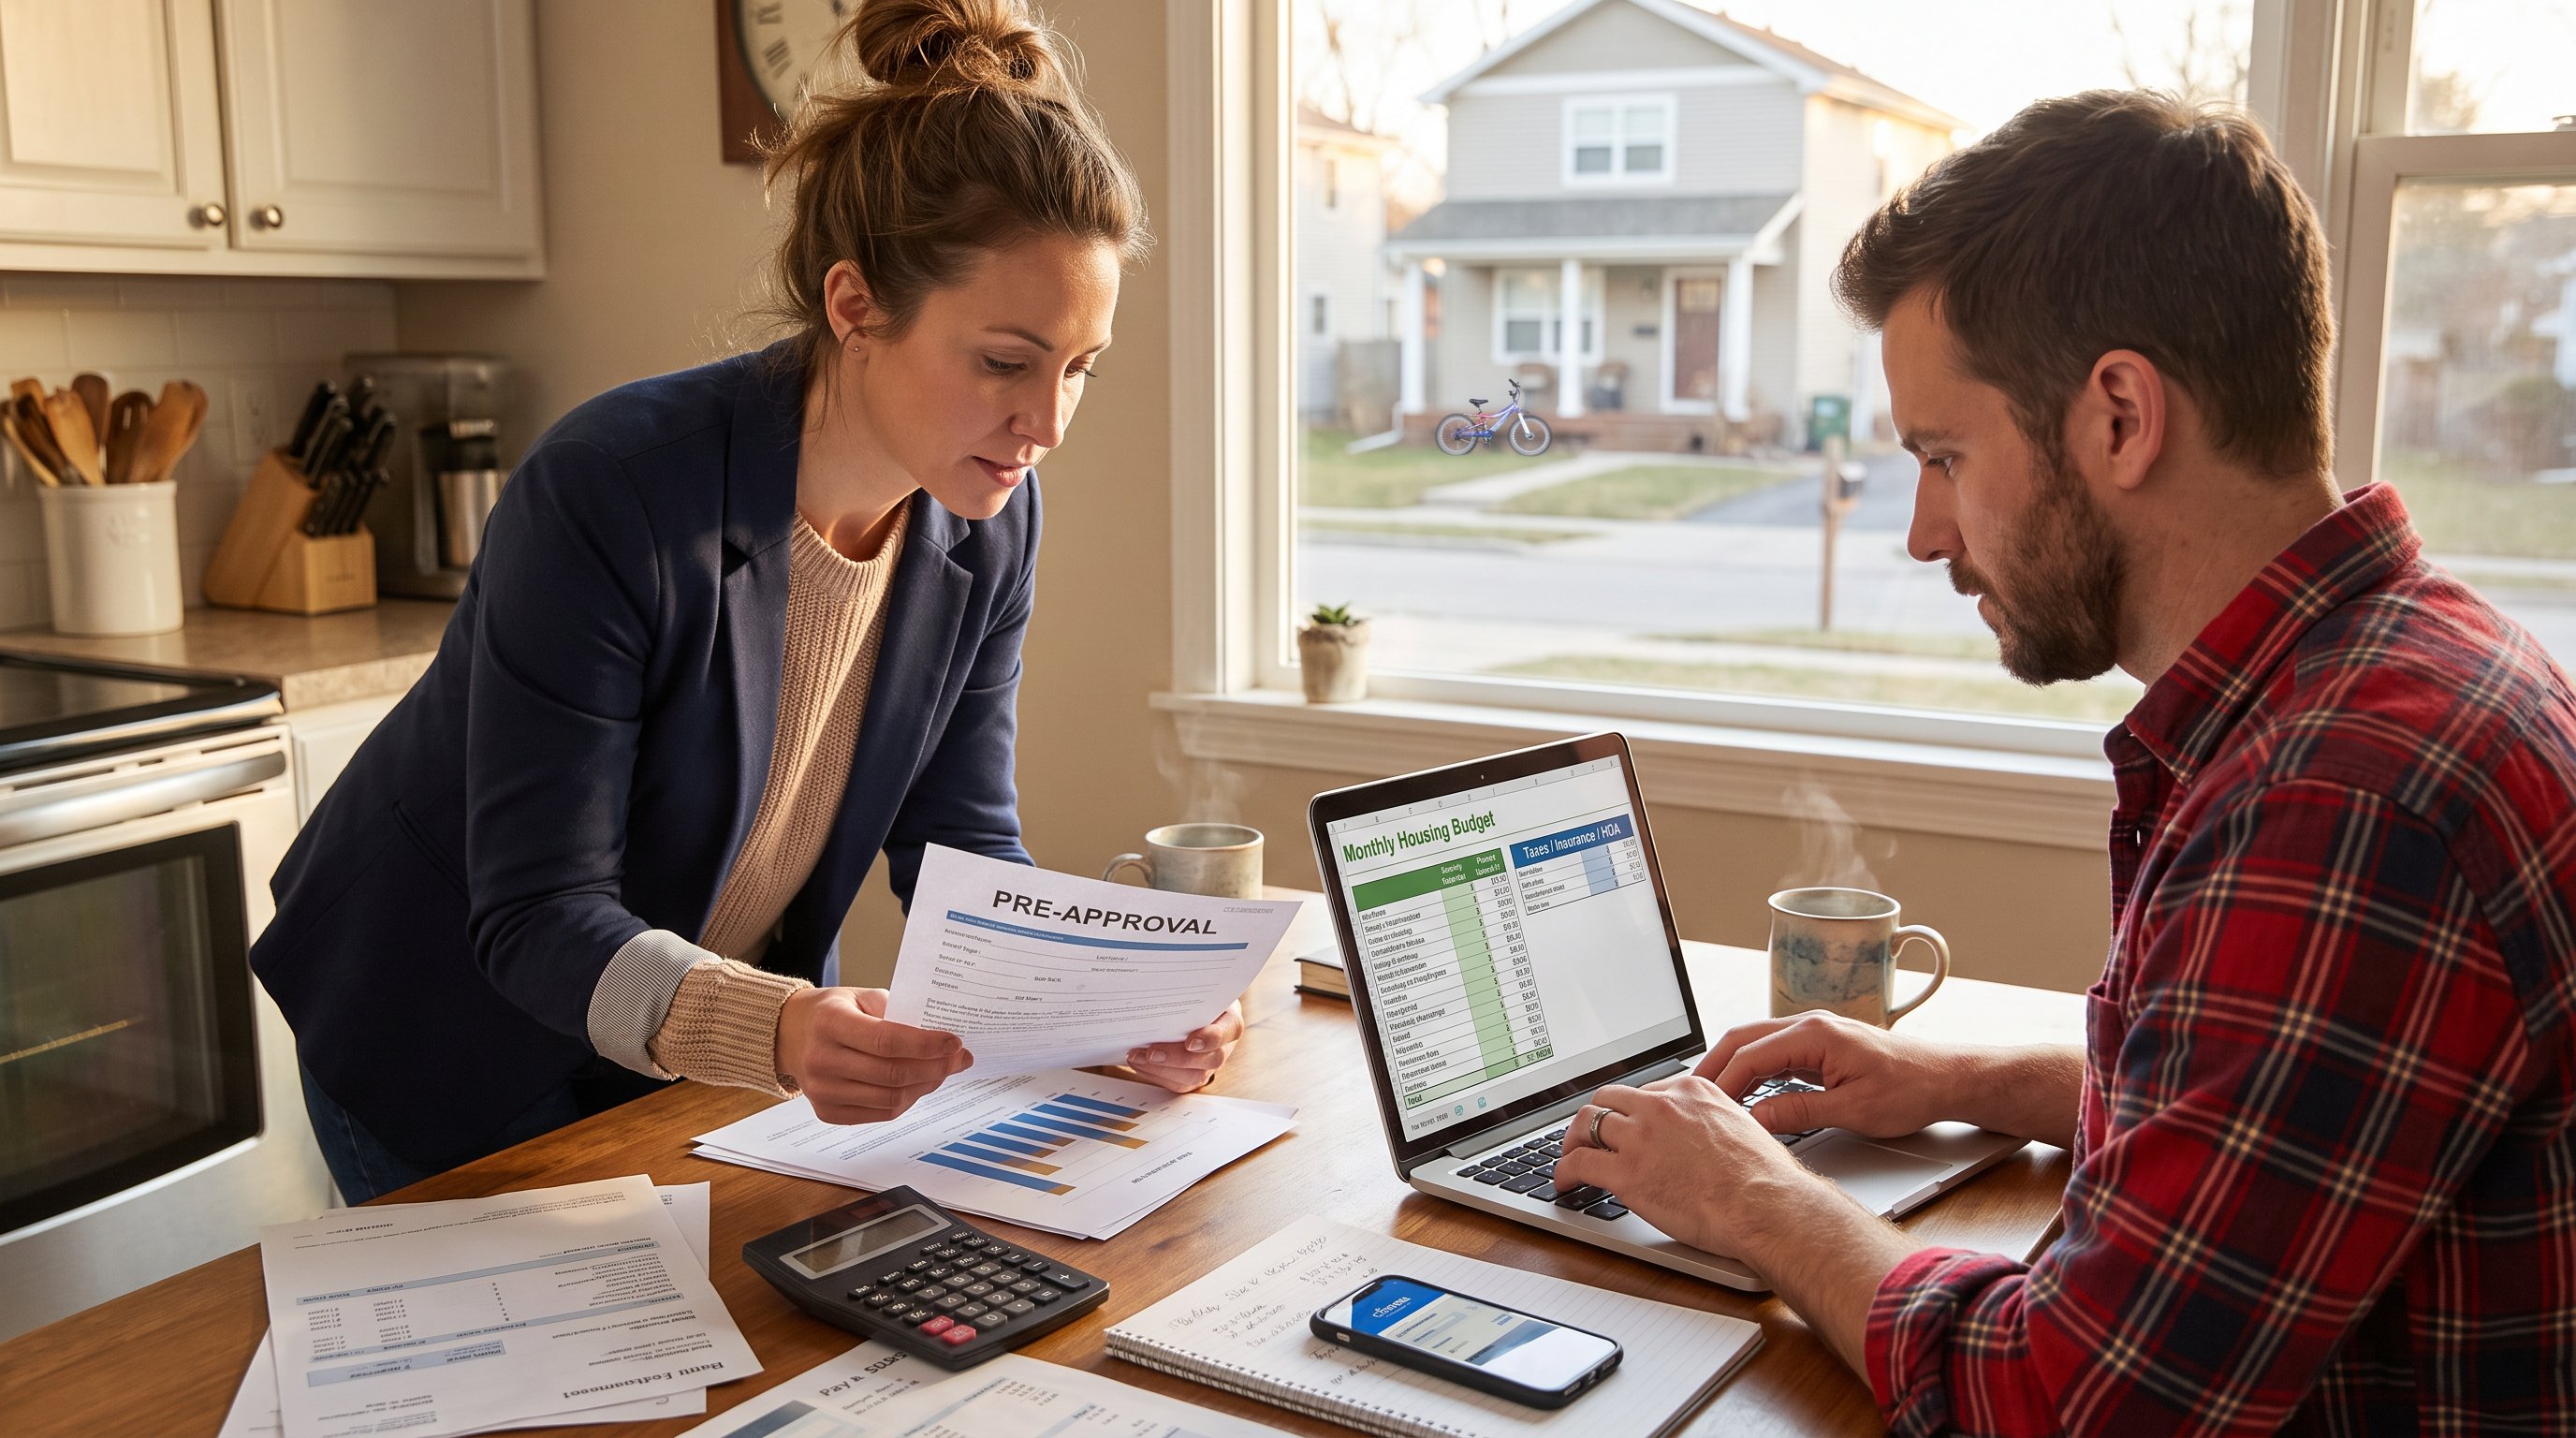
Direct answer: build a monthly housing number that works in practice, then seek lender preapproval in that range, not the highest they’ll offer.
Start with take-home affordability: subtract non-discretionary monthly costs and a 3–6 month emergency savings target from income: the remainder defines available funds for housing and wants. Use affordability calculators to run scenarios: lower down payment increases monthly cost: a lower rate reduces it, and an adjustable-rate mortgage raises risk for later adjustments.
Three guiding steps: pick a target payment you feel comfortable with, get a preapproval to confirm the lender’s view, then shop within that cap. Many buyers learn the hard way by letting lenders’ maximums set their price: preapproval gives a technical upper limit, but personal comfort should be lower.
Real example: a buyer with $5,000 gross monthly, $800 existing debts, and $12,000 in savings discovered a comfortable housing payment of $1,200. A lender offered approval for a $2,000 payment. Choosing $1,200 avoided emptying savings and allowed a $300 monthly repair buffer.
Practical link: to align home search with realistic ownership and buying guidance, consult the site’s central resource on buying and owning homes. The short anchor ties naturally into the planning process: consider buying and owning guidance when setting long-term assumptions.
Conclusion
A realistic home-buying budget starts with honest arithmetic: gross income, true debts, verified savings, and a full accounting of ownership costs. Buyers should build a comfortable monthly payment, get preapproved at that level, and leave room for repairs and life’s surprises. When numbers and comfort match, a house becomes a stable home instead of a financial burden.