 Qyndarix Thalendros
When Renovating a Modest Home Makes Financial Sense starts with one clear fact: modest homes earn the best payback from targeted, pragmatic upgrades rather than luxury overhauls. The reader will learn when a renovation produces a measurable financial return and when it merely increases monthly expenses. This guide frames decisions around three pillars: homeowner goals, the house’s physical condition, and local resale ceilings. It uses 2025–2026 cost‑versus‑value trends and practical budgeting rules so homeowners can choose cost‑effective projects with predictable outcomes.
Key Takeaways
- Renovating a modest home makes financial sense when the homeowner’s goals, the house’s condition, and local market values align.
- Prioritize repairs and midrange updates like roof, HVAC, and curb appeal to ensure safety and marketability before luxury renovations.
- Small-to-midrange projects such as garage door replacements and steel entry doors yield the highest return on investment for modest homes.
- Use conservative budgeting with local resale ceilings and include contingencies to avoid overspending and loss of profit.
- Choose low-cost financing options to protect net gains, and schedule renovations strategically to maximize resale value.
- Focus on practical, neutral updates and avoid luxury upgrades that exceed neighborhood standards to ensure cost-effective renovations.
Assessing Your Financial Goals, Home Condition, And Local Market
Fact first: a renovation makes financial sense only when goals, condition, and market align. The homeowner must state the goal, sell soon, stay and improve cash flow, or boost comfort, and then match projects to that timeline. If they plan to sell within three years, prioritize repairs and midrange updates that bring the house up to neighborhood norms: if they plan to live in the house long term, choose durability and energy savings.
Start with a fast, honest condition audit: roof, foundation, HVAC, electrical, and plumbing. These are non‑negotiable because buyers and inspectors flag them first. A leaking roof or old wiring reduces marketability and can erase any cosmetic gains. For an example, one homeowner replaced a failing furnace for $5,400 and avoided a last‑minute sale credit of $8,200 their inspector would have demanded, a direct, measurable save.
Compare the house to three recent nearby sales in the same price band. If the home already sits at or above the neighborhood median, big luxury upgrades will likely be lost value. Conversely, if the home is below standards, older siding, worn kitchen finishes, or single‑pane windows, small-to-midrange fixes can push it into the competitive tier without overbuilding. He can use the site’s resources for budgeting and ownership basics, including a short primer on long‑term ownership, by following practical guidance for a homeowner’s decisions with a linked resource for additional context: practical guidance.
Practical checklists help. A concise list, safety repairs, system replacements, curb appeal, then interiors, keeps focus. That order preserves value and prevents wasted spending. Finally, assume conservatively: estimate resale gains below national averages for high‑end work in modest neighborhoods and add a 10–20% contingency for unexpected issues discovered during remodeling.
Cost–Benefit Analysis: Which Renovations Actually Boost Value For Modest Homes
Answer up front: small, exterior, and modest midrange projects return the most value for modest homes. National trends for 2025–2026 show dramatic paybacks for select items. The homeowner should choose projects with documented ROI rather than gut‑driven luxury work.
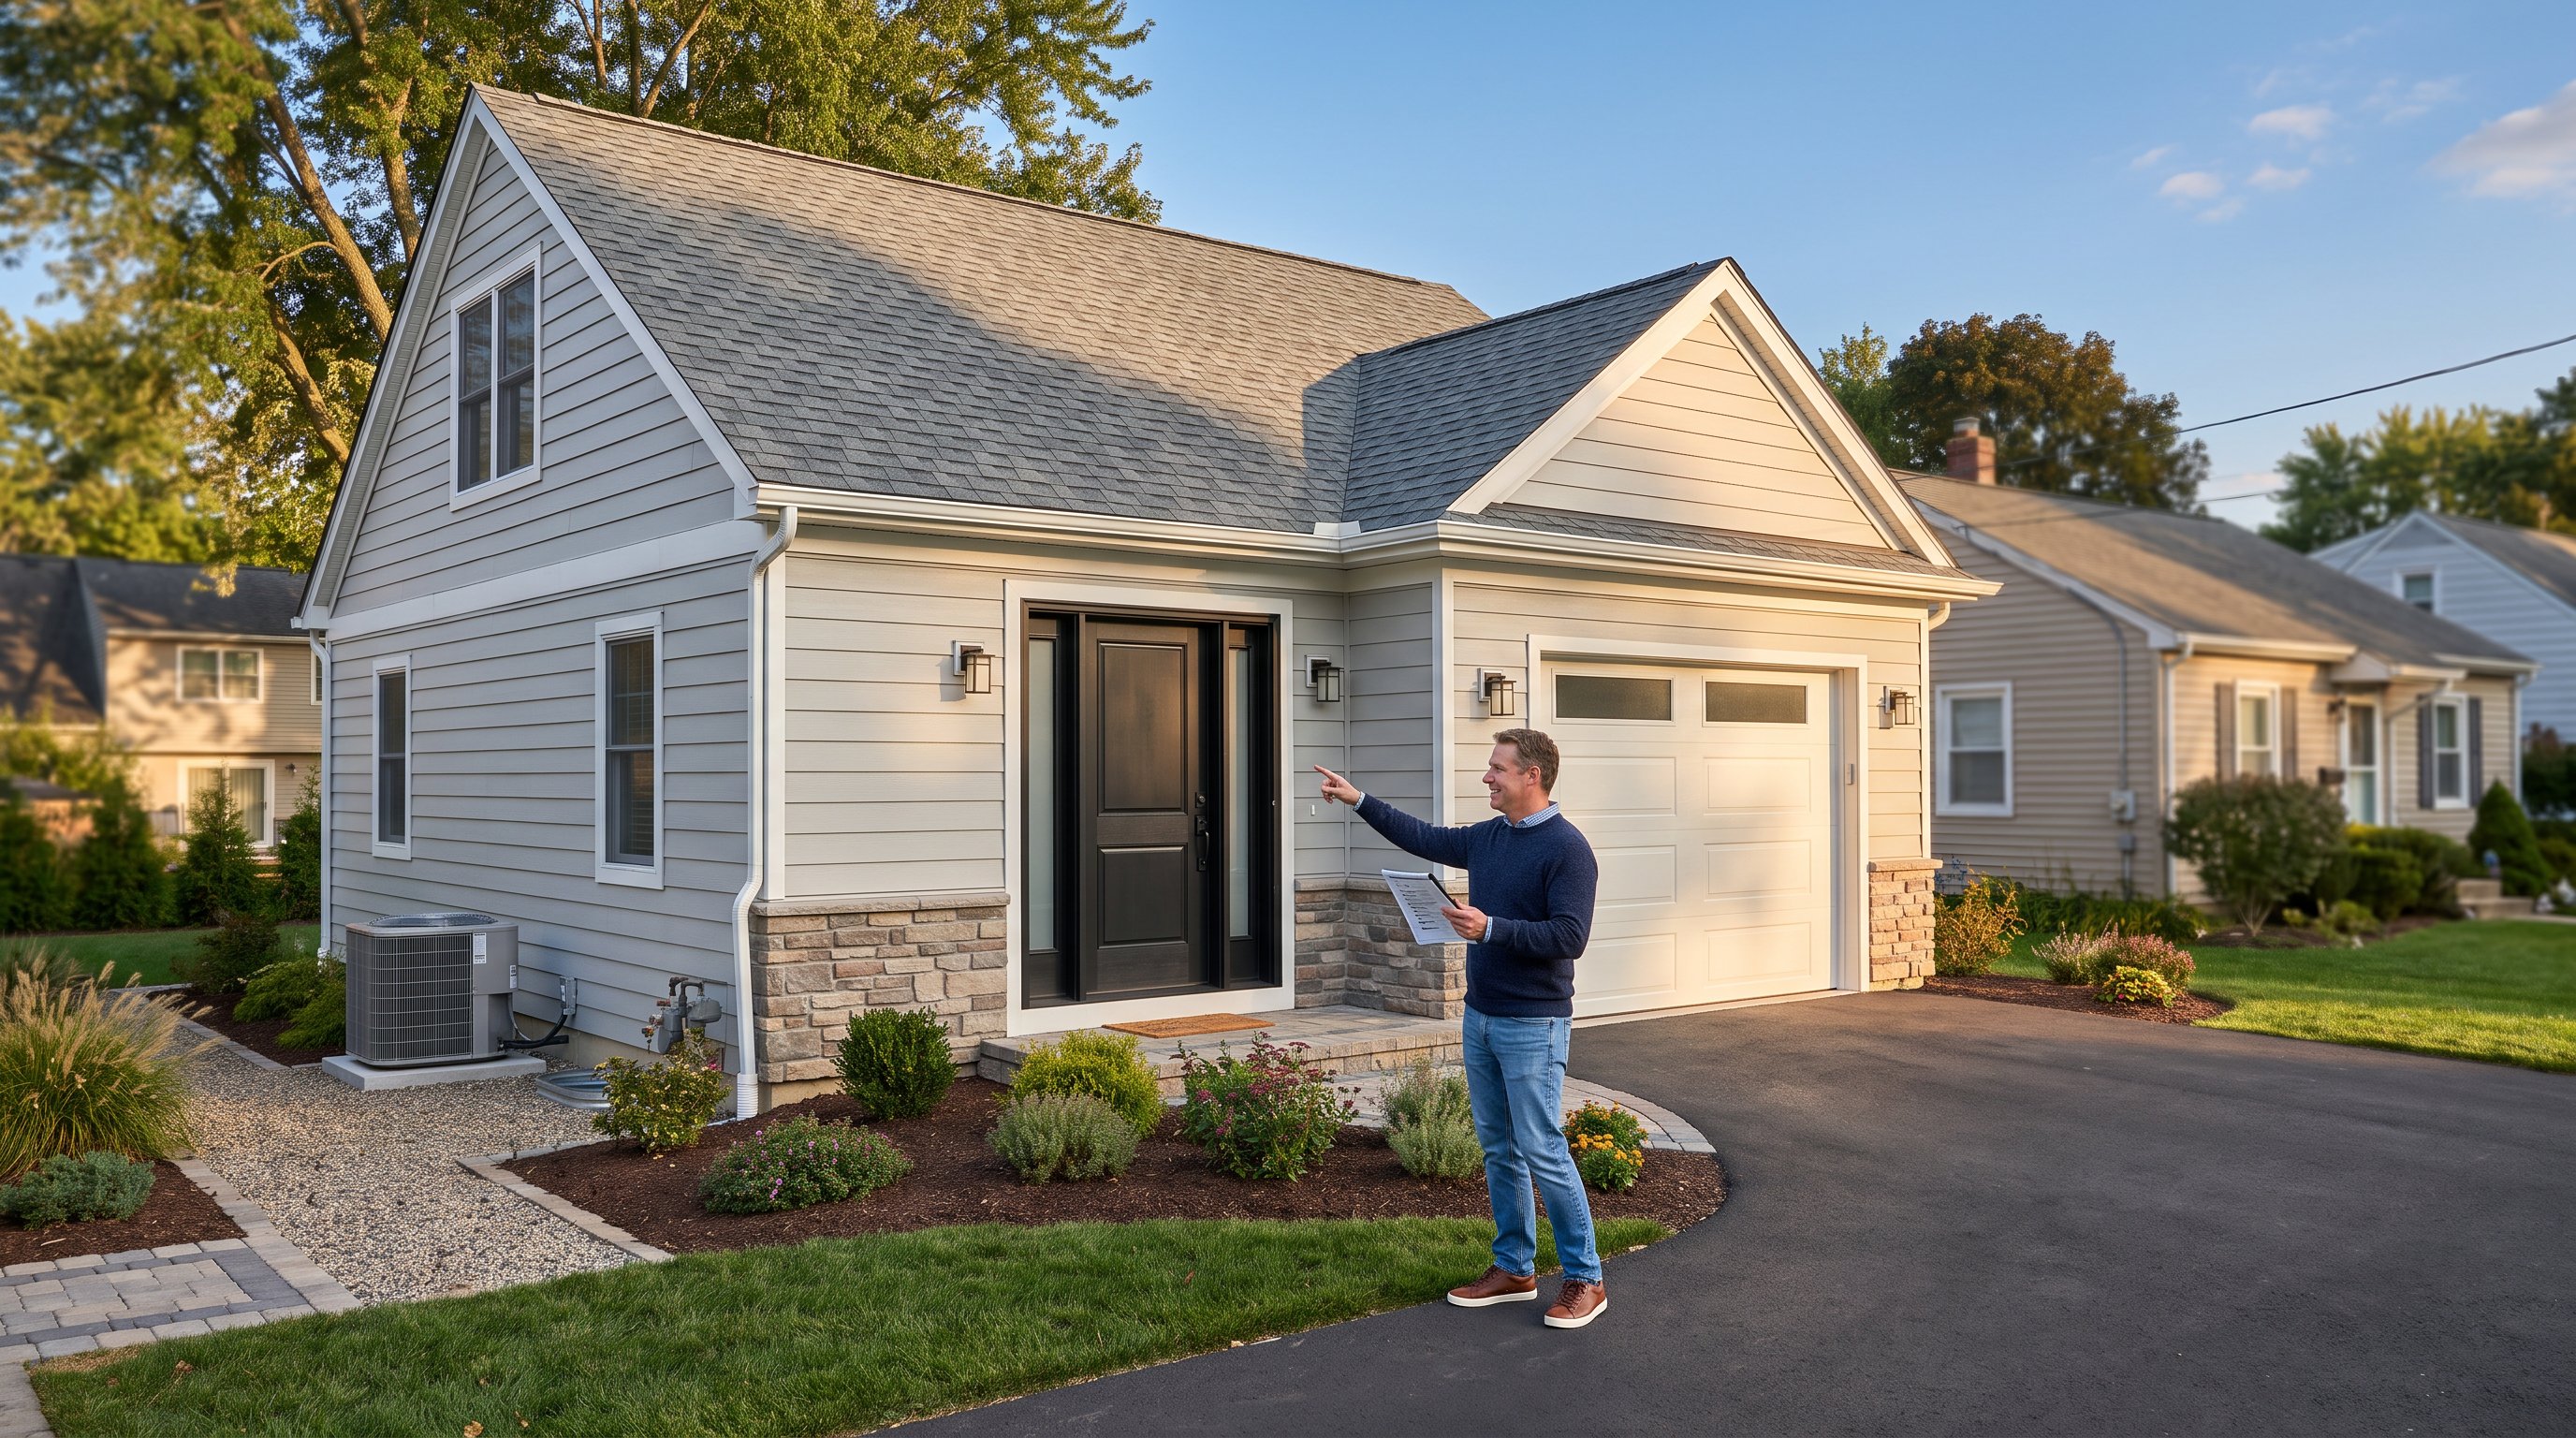
High‑ROI examples with concrete numbers: garage door replacement often recoups roughly 268–303% of cost, and a steel entry door typically returns about 216–226%. Manufactured stone veneer and fiber‑cement siding commonly yield near 200% and 99–114% respectively. A minor midrange kitchen remodel recoups roughly 94–113% depending on scope and materials. By contrast, major kitchen overhauls, upscale baths, and additions typically return 40–70% and are lifestyle investments more than profit centers.
A simple cost–benefit method: estimate project cost, then apply the conservative local ROI (use recent comps to adjust national averages). He should calculate the breakeven resale value that justifies the spend. For instance, spending $8,000 on a new garage door with a 250% expected recoup means roughly $20,000 added value, often safe in a modest neighborhood.
Tactically, prioritize curb appeal items that change perception quickly: new siding, an updated front door, controlled landscaping. Interior updates should focus on kitchens and baths at the midrange level, new cabinet fronts, refreshed counters, and durable floors, rather than bespoke finishes. For targeted ideas and room‑level priorities, consult the site’s pieces on practical exterior and interior refreshes, such as articles on exterior renovations and affordable home makeover ideas.
Warning: aesthetic trends can shift fast. He should avoid adding ultra‑niche features that appeal to few buyers. A modest, neutral palette and proven materials reduce risk and maximize buyer pool.
Financing, Budgeting And Timing: How To Avoid Overbuilding For Your Neighborhood
Key insight first: financing method and timing directly influence net ROI. Low‑cost financing or cash preserves projected gains: high‑interest credit can turn a profitable project into a money loser. He should pick financing that keeps carrying costs low and schedule major work close to a sale only when local data show strong ROI.
Budget with conservative resale assumptions. Use local comparables to cap the home’s post‑renovation value and never assume price gains above that ceiling. Typical ROI per dollar spent across many projects sits near 74% nationally: modest neighborhoods often fall below that for luxury upgrades. A practical rule: cap renovation spend to the amount that keeps the projected value below the neighborhood top quartile.
Payment options matter: cash, a 15‑year home equity loan, or a low‑interest HELOC tend to preserve net gains. High‑rate personal loans and credit cards quickly erode profit: if a homeowner needs options, an article on ways to pay can verify loan pros and cons and creative funding: pay for renovations.
Timing strategy: schedule exterior and curb projects earlier to maximize photos and first impressions for listing. Interior staging and minor kitchen refreshes should finish within six weeks of listing to keep the property fresh. Avoid major structural additions shortly before selling unless market comps show consistent premium pricing for larger footprints in the neighborhood.
Practical budgeting tools reduce risk. Use an itemized spreadsheet with: quote, contingency (10–20%), carrying cost estimate, and conservative resale uplift. He can also use the site’s planning content for step‑by‑step project organization, including a guide on how to plan a renovation and a post on budget-friendly upgrades. Those resources help keep scope tight and avoid the classic pitfall of letting small overruns cascade into large, unprofitable upgrades.
Conclusion
Insight: for modest homes, measured upgrades beat ambitious remodels for financial returns. He should fix safety and systems first, pick high‑ROI curb or midrange interior projects next, and finance sensibly to protect gains. Thoughtful planning and local market discipline turn modest renovations into real value rather than an emotional money pit.