 Qyndarix Thalendros
How much down payment do you need for a home? Most buyers should expect to put down between 3% and 20% of the purchase price. This article gives clear ranges, explains how down payments affect monthly costs and mortgage insurance, and highlights programs that let buyers lower their upfront cash in 2026.
Key Takeaways
- Most homebuyers need a down payment between 3% and 20% of the purchase price, with some loans like VA and USDA offering 0% down options for eligible buyers.
- Putting down 20% typically eliminates private mortgage insurance (PMI) on conventional loans, reducing monthly payments and long-term costs.
- FHA loans require a minimum 3.5% down payment but carry mortgage insurance premiums that may increase lifetime costs compared to conventional loans.
- Buyers can lower upfront cash by using grants, gift funds, and specialized loan programs, but should carefully review eligibility and program rules.
- Choosing a down payment amount involves balancing immediate affordability with future interest and insurance expenses to suit financial goals.
- Understanding loan types and their down payment requirements helps buyers select the best mortgage for their situation and optimize monthly costs.
How Much Down Payment Do You Need? Quick Ranges And What They Mean
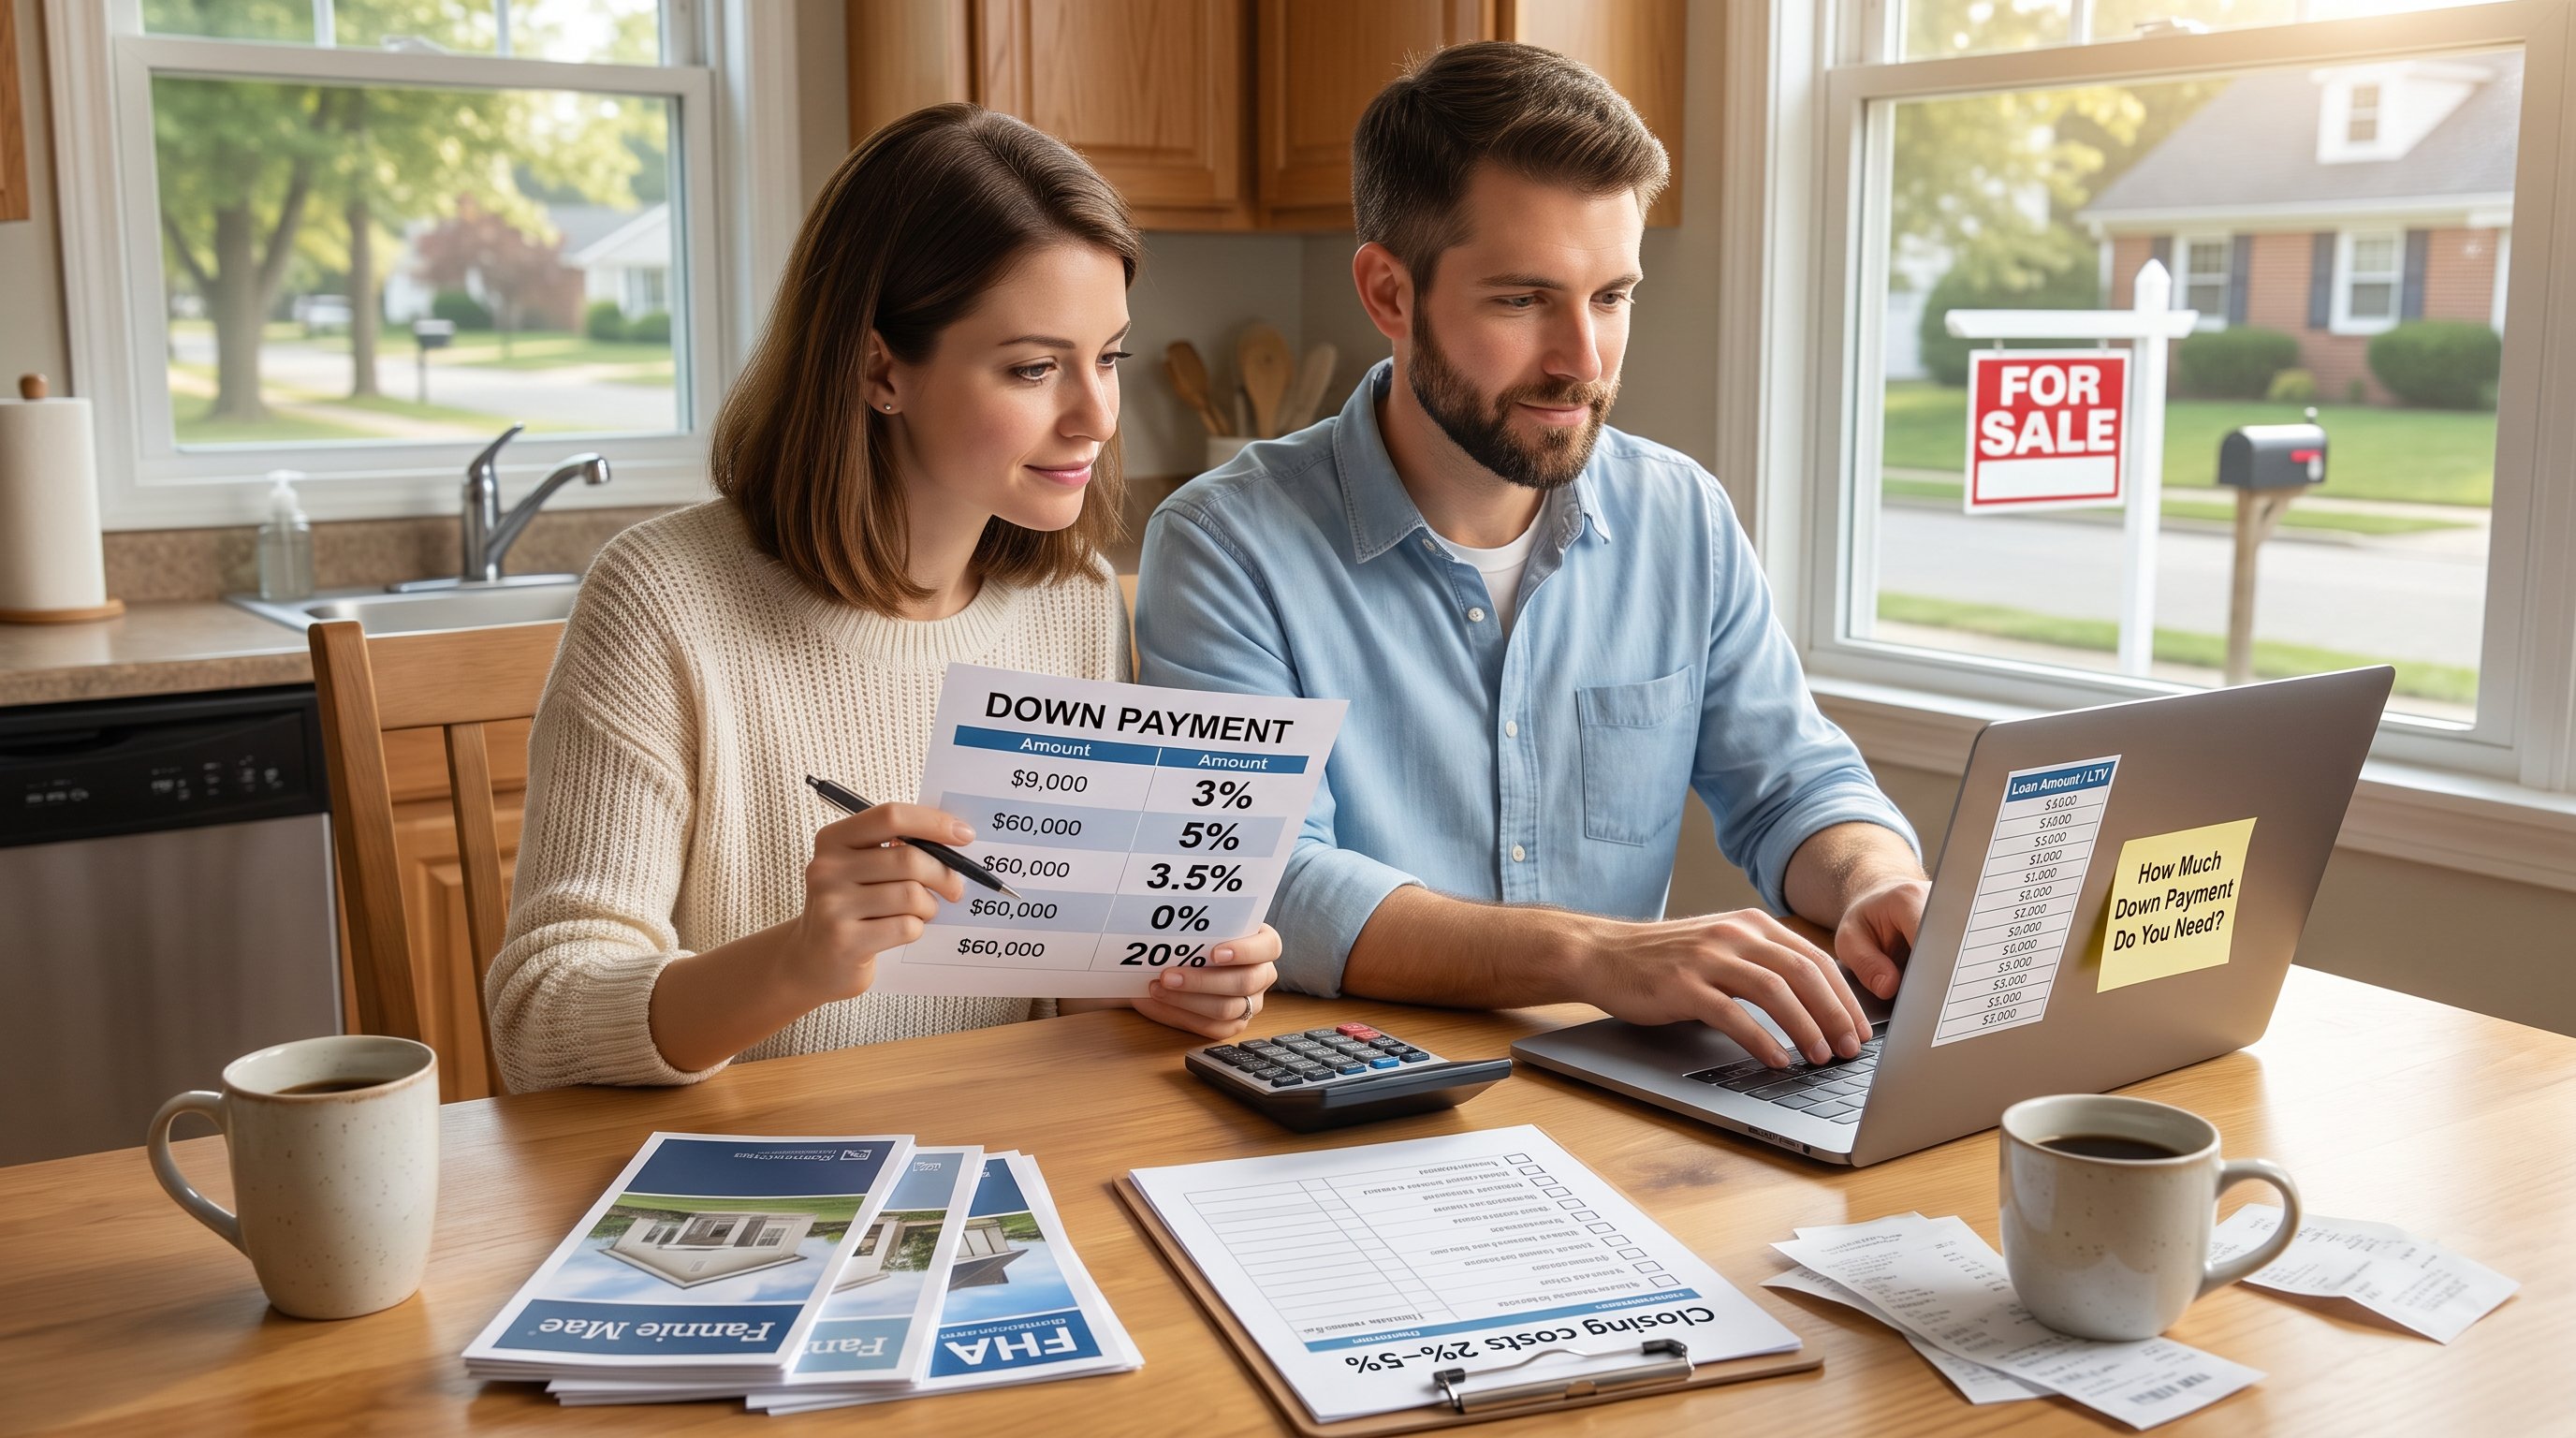
Fact: Typical down payments fall between 3% and 20%, with zeros possible for specific programs. For a $300,000 home, that translates into roughly $9,000 at 3% and $60,000 at 20%, a concrete way to picture trade-offs.
3%–5%: Many conventional lenders offer 3% minimums for qualified buyers, and some common programs advertise 3% as the entry point. This maximizes buying power but usually triggers private mortgage insurance (PMI), which adds to the monthly bill.
3.5%: FHA loans commonly require 3.5% for borrowers with credit scores of 580 or higher. FHA’s mortgage insurance premium (MIP) is charged separately and often raises the lifetime cost compared with conventional loans that cancel PMI after reaching 20% equity.
0%: Eligible veterans and active-duty service members can access VA loans with zero down. Similarly, USDA loans can offer 0% for qualifying rural-area buyers who meet income limits.
10%–20%+: Putting down 10% reduces monthly principal and interest meaningfully: 20% and above usually eliminates PMI on conventional loans. For buyers who value lower monthly payments and easier refinance options, reaching 20% is a clear milestone.
Practical note: choosing a down payment is a decision between higher monthly affordability now and long-term interest and insurance costs. Many middle-income buyers use lower down payments to enter the market sooner, while others save for 20% to reduce recurring costs.
How Down Payments Work — The Basics Every Homebuyer Should Know
Fact: A down payment is the buyer’s equity at closing: the lender finances the remainder. That simple fact determines loan-to-value (LTV), which drives interest rates, mortgage insurance, and refinancing options.
If a buyer puts 5% down on a $400,000 house, the loan starts at $380,000 and the LTV is 95%. Higher LTVs (smaller down payments) bring more risk to lenders, and they respond by charging PMI or program-specific fees like FHA’s MIP or VA funding fees.
Mortgage insurance: PMI on conventional loans protects the lender and typically ends once the borrower reaches 20% equity through payments or appreciation. FHA’s MIP usually lasts longer and sometimes the life of the loan unless refinanced. VA loans charge a one-time funding fee instead of monthly mortgage insurance: USDA loans have a guarantee fee.
Credit and documentation matter: lenders assess income, assets, credit score, and source of down payment. Gift funds are allowed under many programs but require a paper trail. Buyers who use assistance programs must understand restrictions: some grants have occupancy, income, or first-time buyer rules.
Real-world tip: many buyers misjudge closing costs as part of the down payment. Closing costs are separate and usually run 2%–5% of the purchase price. Planning for both prevents last-minute scramble or canceled deals.
Typical Down Payments By Loan Type
Fact: Loan type largely determines minimum down payment and associated fees. The table below shows the typical minimums and the trade-offs buyers face.
| Loan type | Typical minimum down payment |
|---|---|
| Conventional | 3%–5%: 20% avoids PMI |
| FHA | 3.5% (credit ≥580): 10% (credit 500–579) |
| VA | 0% for eligible borrowers |
| USDA | 0% in eligible areas with income limits |
The following subsections explain the nuances buyers meet when choosing a loan.
Conventional Loans: Standard Percentages, Private Mortgage Insurance, And Exceptions
Fact: Conventional loans can accept as little as 3% down, but PMI applies until the borrower reaches 20% equity.
Conventional 3% programs exist for first-time and low-wealth buyers. Examples include lender-specific offerings that pair a small down payment with income or geographic limits. Most lenders, but, feel comfortable with 5% as a de facto standard for wider availability.
PMI mechanics: PMI usually costs 0.3%–1.5% of the original loan amount annually. On a $250,000 loan, that could be $75–$312 monthly. Borrowers can often request PMI cancellation when loan-to-value reaches 80% via payments or a new appraisal.
Exceptions: Some conventional programs, like Fannie Mae’s HomeReady or Freddie Mac’s Home Possible, allow low down payments with income caps or mortgage insurance that has lower premiums. Buyers should compare lender offers and read the mortgage insurance rules carefully.
Real example: a teacher bought a $275,000 house with 3% down in 2024 using a HomeReady-style program. Her first-year PMI was about $95 monthly: she prioritized extra payments to hit 80% LTV sooner and cancel PMI after four years.
FHA, VA, And USDA Loans: Lower Down Payment Options And Eligibility Considerations
Fact: FHA, VA, and USDA loans enable very low or zero down payments but carry program fees or eligibility rules.
FHA: Requires 3.5% down for borrowers with credit scores at or above 580. Borrowers with lower scores typically need 10%. FHA charges an upfront MIP and monthly MIP: the upfront portion can often be rolled into the loan.
VA: Offers 0% down for eligible veterans, active-duty members, and some surviving spouses. The VA charges a one-time funding fee (exempt for some disabled veterans) that depends on down payment size and military category.
USDA: Allows 0% down for properties in eligible areas and for buyers who meet income limits. The USDA charges an upfront guarantee fee plus an annual fee, both smaller than FHA MIP in many cases.
Eligibility matters: VA requires service documentation: USDA uses income charts and property eligibility maps: FHA has credit and debt-to-income limits. Buyers should gather the necessary paperwork early to speed underwriting.
Smart Ways To Lower Your Upfront Cost: Grants, Gifts, And Loan Programs
Fact: Grants, gift funds, and assistance programs can reduce the cash needed at closing, sometimes to zero.
Down payment assistance (DPA): State and local housing agencies offer grants, forgivable second mortgages, or deferred loans to qualified buyers. For example, a city program might give $10,000 in a forgivable second mortgage if the buyer stays in the home ten years.
Gift funds: Many programs permit family gifts with a signed gift letter and bank statements. Lenders look for clear donor documentation and proof that funds aren’t borrowed.
Special programs: HomeReady and Home Possible provide low down payment conventional options for income-qualified buyers. Veterans can combine VA zero-down with some community assistance programs to cover closing costs.
Practical link placement: For a broader step-by-step on buying and owning a home, middle-income buyers often consult the site’s central resource. The phrase practical buying guide links to a helpful pillar page with program checklists and state-by-state pointers.
Budgeting help: To set a down payment target, readers should pair this guidance with a tailored budget. The site’s home-buying budget article shows how to translate savings goals into monthly targets. After purchase, understanding ongoing costs matters: see the monthly cost guide for typical figures such as taxes, insurance, and maintenance.
Warning: some assistance programs have recapture clauses or strict resale rules. Always read program contracts and ask a housing counselor about long-term implications.
Conclusion
Insight: Minimum down payments range from 0% to 3.5% depending on the loan, while 5%–20% is common for conventional buyers who want to control monthly costs and avoid PMI. Buyers should balance short-term affordability against long-term interest and insurance costs, and they should explore grants, gifts, and program options before locking in a plan.