 Qyndarix Thalendros
The true monthly cost of owning a home often surprises buyers. Beyond principal and interest, homeowners pay taxes, insurance, utilities, HOA dues, maintenance, and occasional PMI. This article breaks down each line item with 2026 numbers, shows regional ranges, and gives a step‑by‑step calculation readers can use today. It focuses on clear, real figures and practical actions to reduce monthly burden without glossing over common mistakes and emergency needs.
Key Takeaways
- The true monthly cost of owning a home includes mortgage principal and interest, taxes, insurance, utilities, HOA fees, maintenance, and sometimes PMI, often surprising buyers with the full amount.
- Mortgage payments typically start with a higher portion going to interest, and PMI adds costs if the down payment is below 20%, increasing the total monthly housing expense.
- Property taxes, homeowners insurance, utilities, and HOA fees can add 30–50% to your mortgage payment, with significant regional variations that impact overall affordability.
- Homeowners should budget at least 1% of the home’s value annually for maintenance and set aside sinking funds for major repairs like roof or HVAC replacements to avoid costly surprises.
- Maintaining an emergency fund covering 3–6 months of housing expenses is critical for unexpected costs, and homeowners must not rely on home equity as emergency cash.
- To reduce true monthly costs, increase your down payment to avoid PMI, shop for better insurance rates, improve home energy efficiency, and choose properties with low maintenance and stable HOA fees.
How Mortgage Payments Actually Break Down
Fact up front: mortgage payments are almost always two parts, principal and interest, and sometimes three when PMI is required. Principal reduces the loan balance. Interest pays the lender. Early years skew heavily to interest: on a 30‑year loan, the first decade can send two-thirds of each payment to interest.
Lenders often collect escrow for property tax and homeowners insurance inside the monthly mortgage payment. That makes the mortgage bill look larger, but those escrowed amounts are not loan interest: they’re held until bills are due. If a borrower puts under 20% down, private mortgage insurance (PMI) typically adds $50–$300+ per month depending on credit and loan size.
Concrete example: on a $450,000 home with 10% down and a 6.5% fixed 30‑year rate, principal and interest are roughly $2,530. Add $400 for taxes and insurance escrow and $125 for PMI, and the lender statement shows about $3,055. That matches real calculator examples that reach $3,525 on similar homes when utilities and maintenance are later included.
Practical warning: borrowers who skip escrow must pay taxes and insurance directly: budgeting discipline matters. For step‑by‑step mortgage math, readers can compare approaches on the site’s budgeting guide about home buying budgets.
Property Taxes, Home Insurance, HOA Fees And Utilities: Monthly Realities
Fact up front: property taxes, homeowners insurance, HOA dues, and utilities often add 30–50% to a mortgage payment. Across the U.S., property tax averages near 1.10% of home value annually: homeowners insurance averages about 0.35%.
Monthly math: on a $450,000 house, 1.10% annual property tax is $4,950 per year, or $413/month. Homeowners insurance at 0.35% is $1,575/year, or $131/month. Add utilities (electric, gas, water, trash, internet) commonly $500–$600/month and HOA dues where applicable $100–$500/month. These numbers explain why many sample totals exceed $4,000/month in metro markets.
HOA caution: monthly HOA fees can spike after special assessments for roof or siding. Before purchase, check HOA reserve studies and minutes, a missed red flag creates surprise bills.
For local buying decisions, readers should pair cost projections with inspection results: the site offers a quick checklist in the guide about home inspections.
Average Tax, Insurance And Utility Ranges By Region
Fact up front: regional differences matter and can change total monthly cost by thousands. California metro areas often have higher taxes, insurance and prices: a recent 2026 estimate placed California ownership near $5,844/month when all costs were included.
Regional examples: the Midwest often shows lower property taxes relative to home value but colder winters raise heating costs. The Northeast can have higher property taxes but older homes frequently need more maintenance. Southern states may have lower taxes but higher homeowners insurance due to hurricanes or hail.
Numbers to remember: homeowners insurance commonly runs $150–$270/month in many U.S. markets: utilities typically range $500–$600/month for a family-sized house. HOA fees vary widely: $100–$500/month is common for condos and some subdivisions, but luxury complexes often charge more.
Practical tip: pair these regional averages with state price data. The site’s state price article helps estimate mortgage lines using local sale prices: average house costs by state.
Maintenance, Repairs And Long‑Term Replacement Costs You Must Fund
Fact up front: maintenance and replacement are recurring costs that owners often underestimate. A reliable rule is 1% of home value annually for routine maintenance, rising toward 3–4% for older houses or those with deferred upkeep.
On a $450,000 home, 1% equals $4,500 per year, or $375/month. That covers paint, HVAC filters, small plumbing fixes, exterior upkeep and seasonal tasks. Major replacements, roof, furnace, water heater, require separate sinking funds. Roof replacement can cost $6,000–$15,000: a new HVAC often $4,000–$10,000.
Honest failure: many owners delay maintenance to save in the short term and later face a $12,000 roof bill that could have been deferred with a $150/month reserve. Treat maintenance like a non‑negotiable utility.
The site’s article on budgeting for repairs shows practical sinking fund schedules and real project cost samples.
Planning For Unexpected Costs: Emergency Funds And Sinking Funds
Fact up front: keep 3–6 months of total housing expenses liquid after closing for unexpected events. This is the commonly recommended cushion to handle job loss, medical bills, or major home repairs.
A worked example: if monthly housing runs $4,000, a 3‑month cushion is $12,000. For longer security, 6 months equals $24,000. For homeowners with single‑income households or variable work, err toward 6 months or more.
Sinking funds: break out monthly contributions for predictable large items. If a roof replacement is expected in 12 years and costs $12,000, save $83/month into a dedicated sinking fund. For a furnace replacement in 10 years at $6,000, save $50/month. These small monthly allocations avoid large lump‑sum shocks.
Practical warning: do not count home equity as emergency cash. Equity is illiquid and may take weeks to access through sale or refinance.
How To Calculate Your Personal True Monthly Homeownership Cost (Step‑By‑Step)
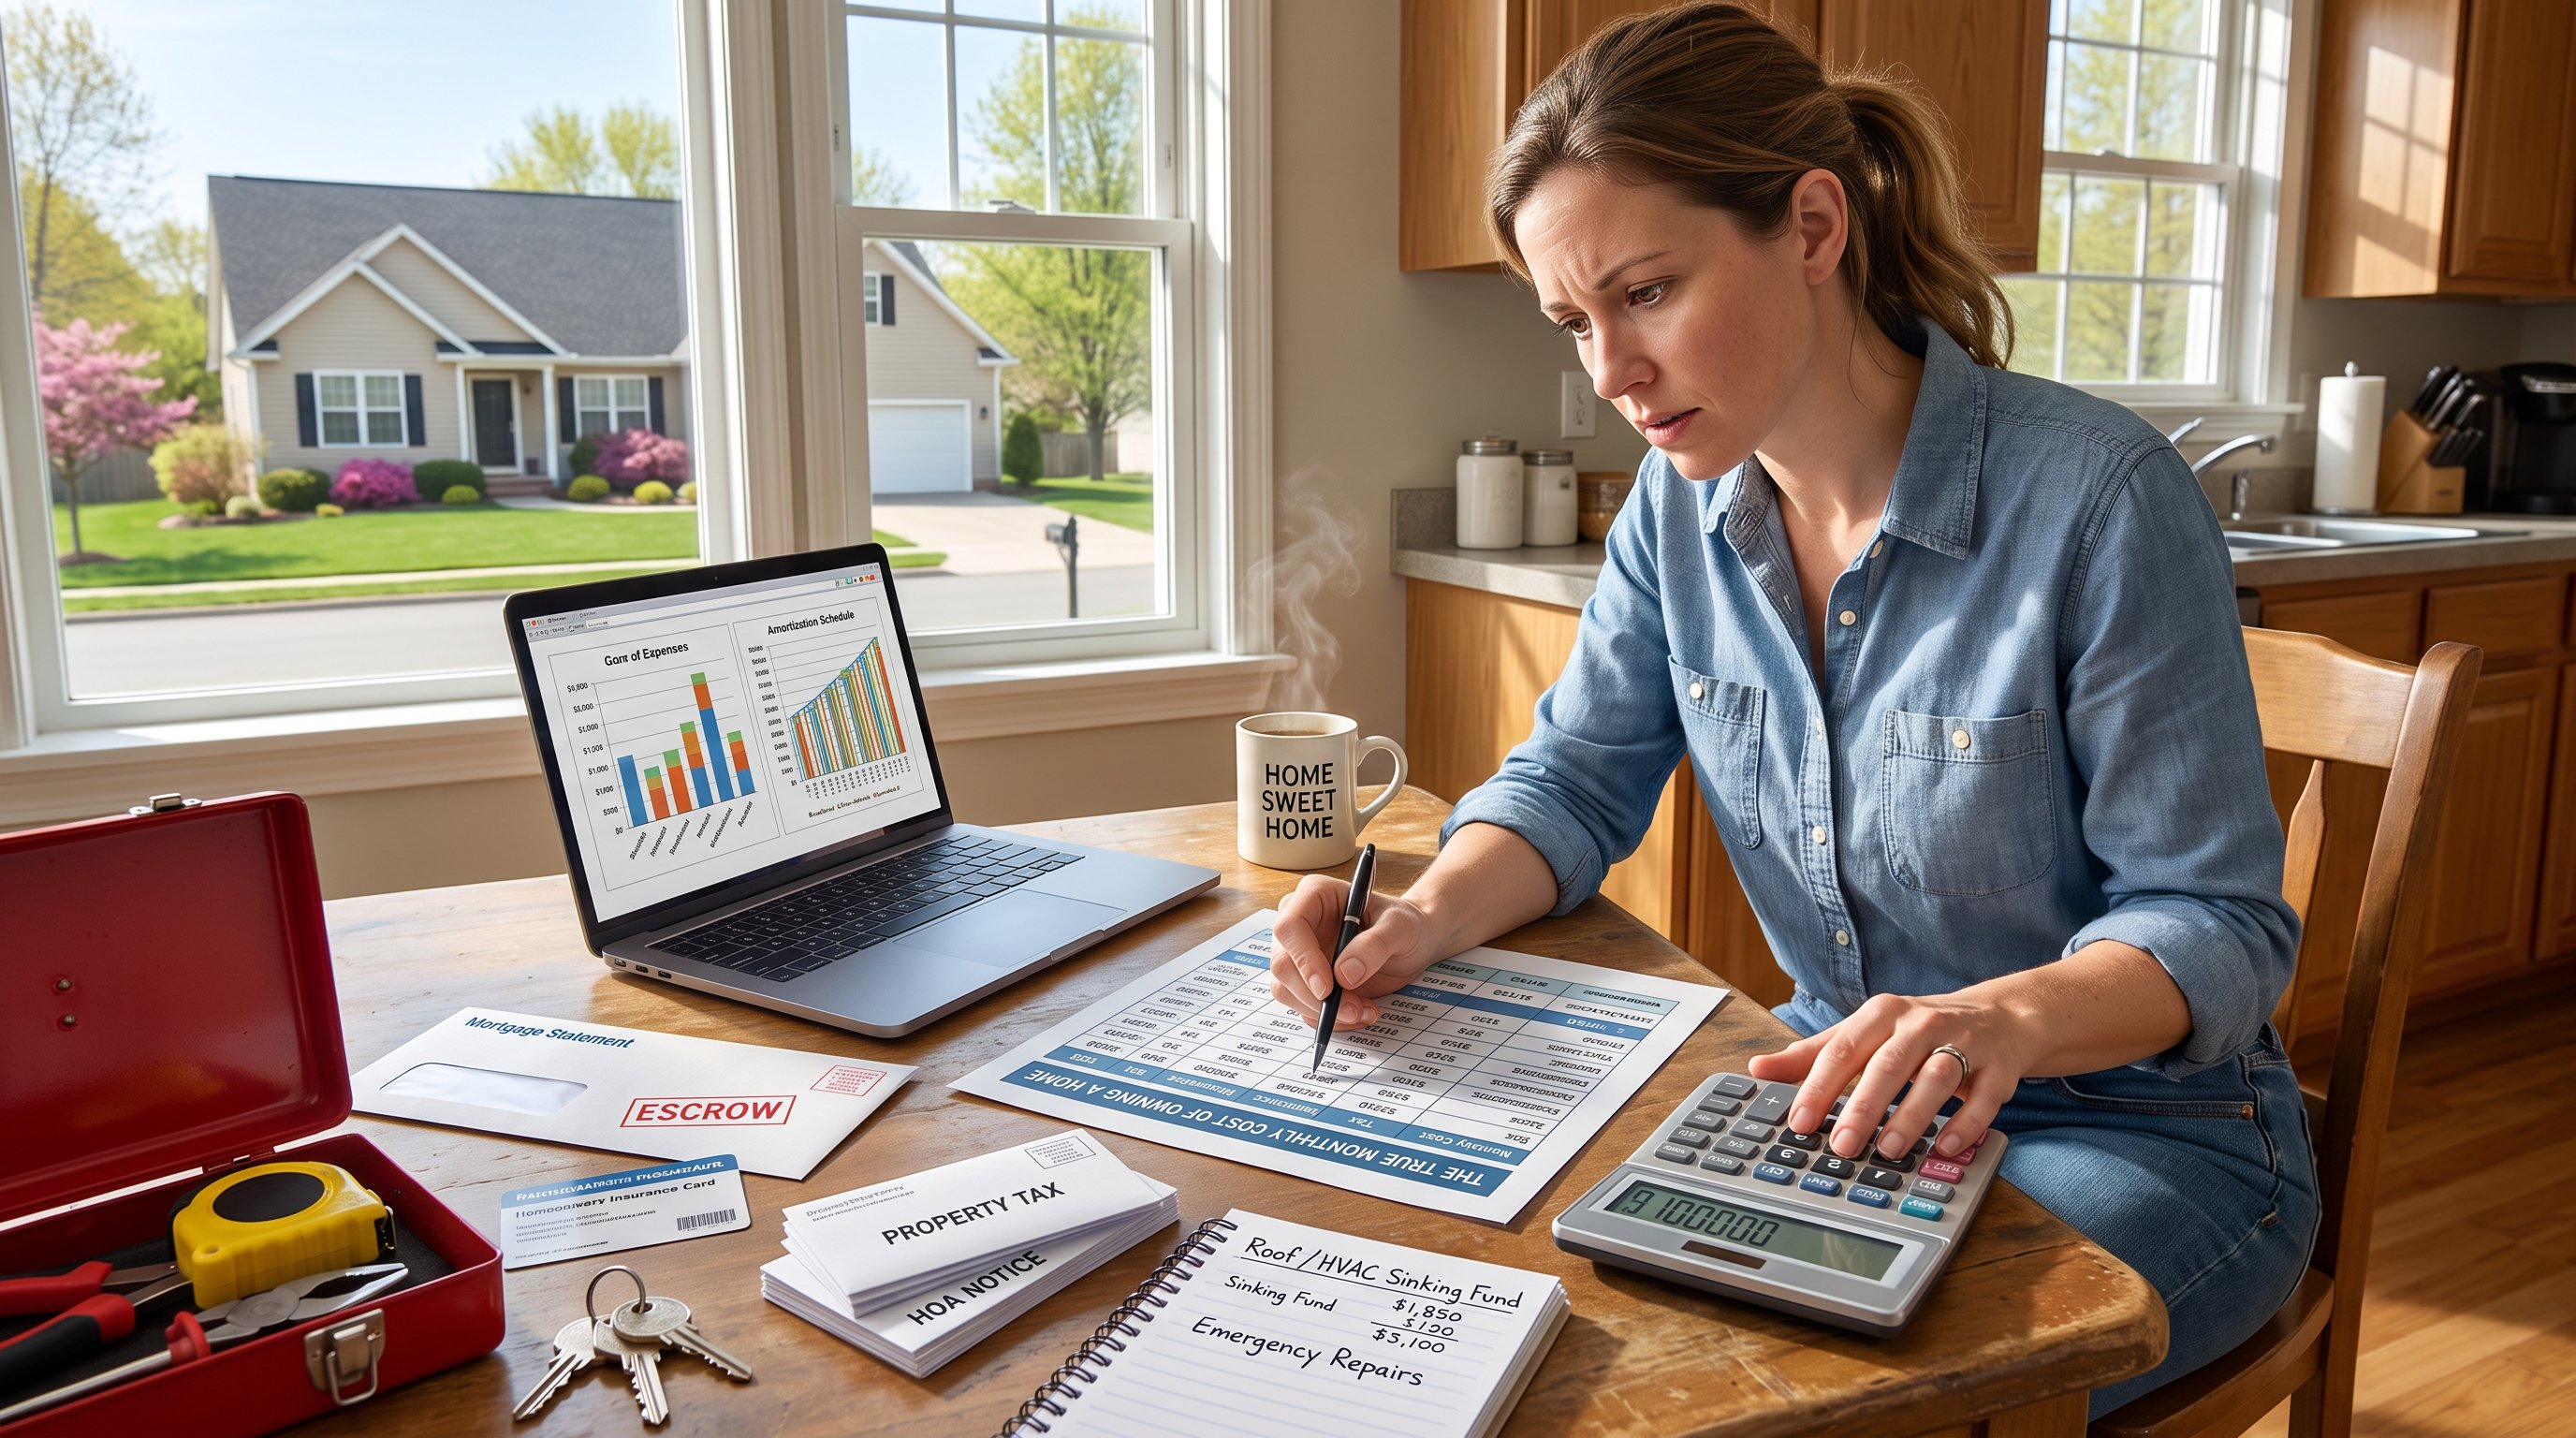
Fact up front: the true monthly cost equals mortgage principal & interest + monthly property tax + monthly insurance + HOA + utilities + maintenance reserve + any PMI.
Step 1, principal & interest: use your loan amount, rate, and term. Many lenders provide an amortization schedule showing exact monthly interest and principal for every payment.
Step 2, taxes & insurance: convert annual amounts to monthly by dividing by 12. If escrow covers them, those amounts appear on the mortgage statement: if not, add them separately.
Step 3, utilities & HOA: tally current bills or local averages. Use recent utility bills for precise numbers: estimate internet and trash if unknown.
Step 4, maintenance & sinking funds: set 1% of home value per year as a baseline for maintenance. Add sinking fund contributions for known future replacements (roof, HVAC, appliances).
Step 5, PMI and extras: include PMI if down payment <20%, plus any service contracts or lender fees.
Concrete calculation example: using a $450,000 price and the cited averages, P&I $2,530 + tax $413 + insurance $131 + utilities $550 + HOA $200 + maintenance reserve $375 + PMI $125 = $4,324/month. That mirrors sample totals in calculators and shows how each line inflates the base mortgage.
Practical Ways To Lower Your Ongoing Monthly Costs
Fact up front: owners can reduce true monthly cost through a few high‑impact moves: higher down payment, shop insurance, reduce energy use, and choose homes with lower maintenance needs.
Tactics with numbers: increase down payment from 10% to 20% to remove PMI, on our $450,000 example that saved roughly $125/month or $1,500/year. Shopping homeowners insurance and bundling policies often saves 10–25% depending on discounts. Upgrading to ENERGY STAR appliances and improving insulation can cut utilities by 10–30%, which may save $50–$150 per month.
Behavioral changes: lower cost by choosing homes with newer roofs, updated mechanicals, and minimal landscaping that needs frequent service. Avoid homes in HOAs with known special assessments, and review reserve funds during due diligence.
Tools and resources: homeowners can compare estimates and find budgeting templates. The site’s central guide offers practical buying and owning tips that pair well with these tactics: see the page on practical guidance for broader strategies. For hands‑on maintenance advice and projections, trusted home renovation resources like Bob Vila provide repair cost context and project checklists.bob vila
Conclusion, short actionable insight: small monthly reserves and one or two strategic choices (larger down payment, better insurance) typically reduce total monthly housing costs more than cutting obvious day‑to‑day expenses. Plan with real numbers, fund sinking accounts, and avoid assuming sale or refinance as an emergency fix.